The decentralized nature of blockchain makes it an open and permissionless global network. However, there are several types of projects in the field, and each one embodies its own rules, community and use cases.
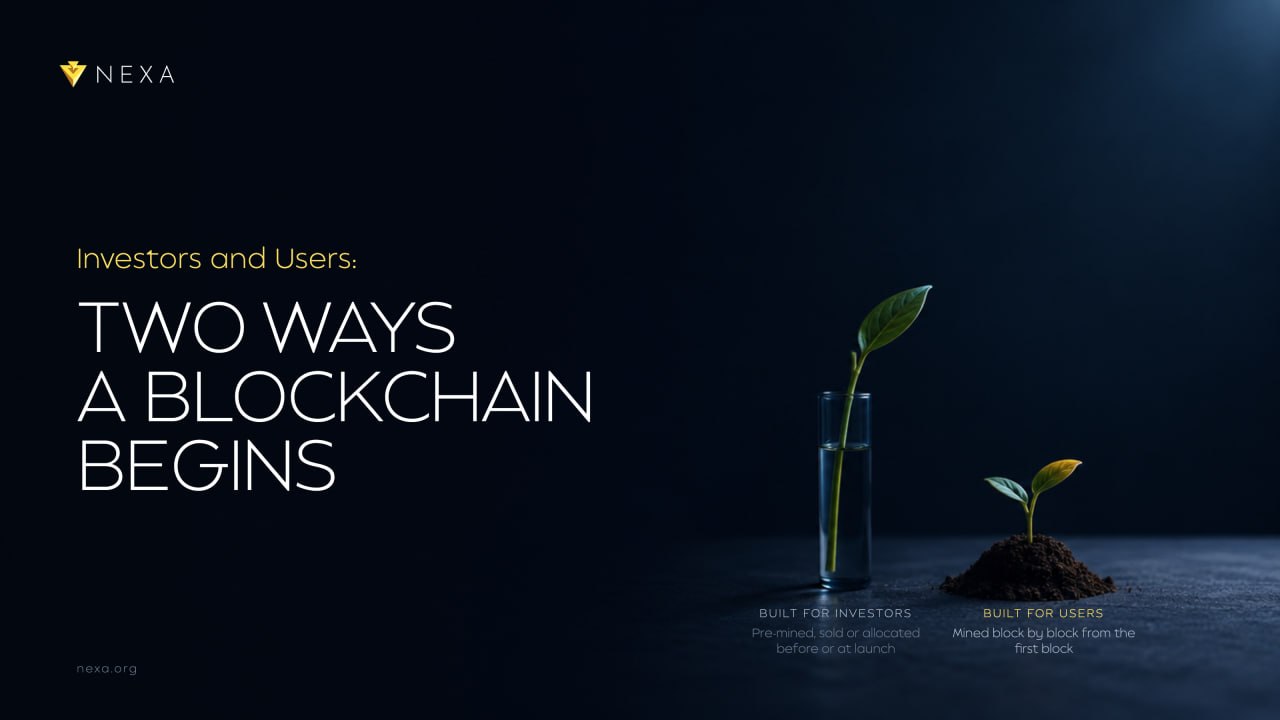
The most important difference between them is who they are built for. Some projects are built to raise money from investors. Others are built for users and are run by the people who secure them.
How Crypto Met Investors
Back in 2017 and 2018, the industry witnessed the ICO bubble. Projects raised capital on-chain by selling new tokens, in exchange for a promise to deliver some kind of product in the future. Most of these token sales ran on the Ethereum blockchain.¹
That was when the broader market and the crypto community poured money into projects of every kind. According to Tokendata, ICOs raised about $5.6 billion in 2017 alone, across 442 completed sales.²
The results were harsh. A Boston College study of ICOs completed before May 2018 estimated that only 44.2% of the startups were still active 120 days after their token sale.³,⁴ The researchers judged this by each startup’s activity on Twitter.
Regulators were already paying attention. On 25 July 2017, the US SEC’s DAO Report concluded that the tokens sold by The DAO were securities, and warned that other token sales could be too.⁵,⁶ It applied the Howey test, which asks whether people invest money in a common enterprise, expecting profits from the efforts of others. That expectation is the heart of the investor model.
Three Types of Projects
Today, most projects fall into one of three types. What separates them is how their coins first came into the world.
-
Tokens on someone else’s blockchain: There are millions of tokens running on all kinds of blockchains. Many raise capital, attract investors, run companies on blockchain rails and present themselves as cryptocurrencies. Of the 25.2 million listed on GeckoTerminal since mid-2021, 13.4 million had stopped trading by the end of 2025.⁷ CoinGecko links the flood of new tokens to launchpads that made low-effort memecoins easy to create.
-
Blockchains launched by companies: A company raises capital, launches its own network and gives coins to its investors in exchange. Most of these blockchains have pre-mined or locked coins allocated to investors, the team and a foundation, released on a schedule. This is common across new tokens. Binance Research found that tokens launched in early 2024 had only about 12% of their supply in circulation on average. In May 2024, it estimated that about $155 billion worth of tokens would unlock between 2024 and 2030.⁸,⁹
-
Fairly launched Proof-of-Work blockchains: These launch without raising capital, and without pre-mining coins or allocating them to investors. Miners put the work into the network, mine blocks and effectively run the blockchain, and in return they receive newly created coins. Its users rely on it for transactions, smart contracts and other applications. Coins are the main incentive for miners to secure it.
The consensus model matters too. In Proof-of-Stake, the coins themselves secure the network. On Ethereum, for example, finality needs votes backed by two-thirds of all staked ETH. One-third of the stake is enough to stall finality, and 51% would let an attacker decide which fork the network follows.¹⁰
On such a network, a large allocation at launch can become a large share of control. In Proof-of-Work, holding coins gives no power to produce blocks. Still, Proof-of-Work alone does not make a launch fair, since some Proof-of-Work chains sold or pre-mined coins before launch.
Investors or Users at a Glance
The first two types mostly follow the investor model, and the third follows the user model. The two models differ from the first coin.
| Question | Built for investors | Built for users |
|---|---|---|
| How do the first coins appear? | Pre-mined, sold or allocated before or at launch | Mined block by block from the first block |
| Who gets coins first? | Investors, the team and a foundation | Miners, under the same rules for everyone |
| Is there a team allocation? | Common, often locked and released over time | None |
| What circulates at launch? | Often a small share, with large unlocks later | Nothing; supply grows only through mining |
| What does success depend on? | Mostly the team delivering what it promised | Mostly people using the network |
Bitcoin Set the Standard
The first cryptocurrency, Bitcoin, was launched fairly and didn’t have any investors. Satoshi Nakamoto announced the white paper, Bitcoin: A Peer-to-Peer Electronic Cash System, on 31 October 2008.¹¹,¹²
The network started with no coins in circulation. The genesis block was mined on 3 January 2009, and its 50 BTC reward can never be spent. The software was released publicly on 9 January.¹³,¹⁴
Miners came to support the idea and to run and secure the network. Two days after the release, Hal Finney mined block 78, the first block mined by a known person other than Satoshi.¹³ For this work, miners were rewarded with the cryptocurrency itself, Bitcoin.
In the white paper, the first transaction in each block creates new coins for the block’s creator. This is also how coins enter circulation, “since there is no central authority to issue them”.¹¹ Satoshi described Proof-of-Work as one-CPU-one-vote, so power over the chain comes from work, not from holding coins.
A fair launch promises everyone the same rules, from the very first block.
Nexa Follows the Same Path
Nexa runs on the same Proof-of-Work model as the original Bitcoin. It launched fairly on 21 June 2022 with 0% of coins allocated to the developers: no pre-mine, no ICO, no team allocation and no dev tax.¹⁵ Every coin is mined through Proof-of-Work.¹⁶
Nexa uses its own mining algorithm, but miners secure it the same way they secure Bitcoin, and its tokenomics are identical to Bitcoin’s.¹⁷ The maximum supply is 21 trillion NEXA, or 2.1 quadrillion satoshis, the same number of smallest units as Bitcoin.¹⁶
Blocks currently arrive about every 2 minutes, and the block reward halves every 1,050,000 blocks, roughly every four years.¹⁶,¹⁷ The first halving came on 1 May 2026 and cut the reward from 10 million to 5 million NEXA per block.¹⁶,¹⁸ By then, half of the total supply had been mined.¹⁸
Development is carried out by the Bitcoin Unlimited team, an organization founded in 2015, which received no coin allocation either.¹⁹ In 2023, Nexa obtained a legal opinion stating that NEXA should be considered a commodity or utility token, not a security.¹⁵ It is a private legal opinion, not a regulator’s ruling.
Built for Users
Nexa embodies the vision of peer-to-peer electronic cash. It innovates on top of Bitcoin’s original UTXO model, built for high scalability, programmability and other core blockchain improvements.
Tokens are native on Nexa and work without special smart contracts or standards such as ERC-20.¹⁷ Smart contracts already run on-chain with Nexa Programming Language (NPL) and NexScript, and in 2024 tests the team reached 50,000 transactions per second.¹⁹ The network is designed to scale to over 10 billion transactions per day, enough capacity for everyone on the planet.¹⁷
How to Check Any Project
Before you buy, use or build on a project, ask a few questions. Most of the answers are in its documentation or on-chain analysis.
-
Was there a pre-mine, a token sale or a private investor round before the public could take part?
-
How much of the supply went to the team, investors and a foundation, and when does it unlock?
-
How much of the maximum supply is in circulation today?
-
Are new coins mined through work, earned through stake, or released by a company?
-
Can anyone run a node, mine or use the network without permission?
-
Is the code open source, and does the network itself enforce the supply rules?
Know What You Hold
It’s worth understanding the difference between a company that runs blockchain infrastructure and issues a token, and a truly decentralized blockchain. The latter is run by people all around the world and needs no permission: anyone can use it or run it.
Raising capital is not wrong in itself, and a fair launch is no guarantee of success. But the launch model decides who a network serves first. So when you look at any cryptocurrency, ask one simple question: is it a company on blockchain rails or is it an actual decentralized cryptocurrency?
Sources
-
Daniel Roberts, “Study: Half of ICO Startups Fail After Four Months,” Yahoo Finance, 10 July 2018. https://finance.yahoo.com/news/half-icos-fail-ico-funding-way-anyway-170800395.html
-
Kai Sedgwick, “ICOs Raise Over $1 Billion in a Month for the First Time,” Bitcoin.com News, 2 January 2018. https://news.bitcoin.com/icos-raise-1-billion-month-first-time/
-
Hugo Benedetti and Leonard Kostovetsky, “Digital Tulips? Returns to Investors in Initial Coin Offerings,” Boston College, SSRN working paper, 2018. https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3182169
-
Olga Kharif, “Half of ICOs Die Within Four Months After Token Sales Finalized,” Bloomberg, 9 July 2018. https://www.bloombergquint.com/onweb/half-of-icos-die-within-four-months-after-token-sales-finalized
-
U.S. Securities and Exchange Commission, “Report of Investigation Pursuant to Section 21(a) of the Securities Exchange Act of 1934: The DAO,” Release No. 34-81207, 25 July 2017. https://www.sec.gov/files/litigation/investreport/34-81207.pdf
-
Morgan Lewis, “SEC Report Asserts Cryptocurrency Tokens Are Securities Under US Law,” 2017. https://www.morganlewis.com/pubs/sec-report-asserts-cryptocurrency-tokens-are-securities-under-us-law
-
Shaun Paul Lee, “Dead Coins: Over 50% of Cryptocurrencies Have Failed,” CoinGecko Research, updated 17 April 2026. https://www.coingecko.com/research/publications/how-many-cryptocurrencies-failed
-
Binance Research, “Low Float & High FDV: How Did We Get Here?” 17 May 2024. https://www.binance.com/en/research/analysis/low-float-and-high-fdv-how-did-we-get-here
-
Chayanika Deka, “Binance Doubles Down on Low Float, High FDV: Calls for Action,” CryptoPotato, 26 May 2024. https://cryptopotato.com/binance-doubles-down-on-low-float-high-fdv-calls-for-action/
-
Ethereum.org, “Proof-of-Stake (PoS),” developer documentation, updated 7 October 2026. Proof-of-stake (PoS) | ethereum.org
-
Satoshi Nakamoto, “Bitcoin: A Peer-to-Peer Electronic Cash System,” 2008. https://bitcoin.org/bitcoin.pdf
-
Satoshi Nakamoto, “Bitcoin P2P e-Cash Paper,” Cryptography Mailing List, 31 October 2008, archived by the Satoshi Nakamoto Institute. Bitcoin P2P e-cash paper | Satoshi Nakamoto Institute
-
Bitcoin Wiki, “2009.” 2009 - Bitcoin Wiki
-
Bitcoin Wiki, “Genesis Block.” Genesis block - Bitcoin Wiki
-
Nexa, “Nexa Articles Database,” entries of 21 June 2022 (launch), 8 March 2023 (fair launch) and 10 May 2023 (legal opinion). https://nexa.org/articles-database
-
Paul Church, “Nexa’s Supply Schedule - Using A Tried and True Model,” Nexa, 19 December 2022. Nexa’s Supply Schedule - Using A Tried and True Model | Nexa Blockchain
-
Nexa, “What Is Nexa?” What is Nexa? | Nexa Blockchain
-
Nexa, “Nexa Monthly Newsletter April 2026: The Inaugural Halving,” Nexa Forum, 2 May 2026. Nexa Monthly Newsletter April 2026: The Inaugural Halving
-
Endo, Nexa Team, “Community Letter 2024,” Nexa, 8 January 2025. https://nexa.org/documents/community_letter_2024.pdf